Singlife Account Closing: 6 Best Alternatives for Your Spare Cash (2026), From Chocolate Finance to Trust, GXS and MariBank
Deals

Singlife Account Closing: 6 Best Alternatives for Your Spare Cash (2026), From Chocolate Finance to Trust, GXS and MariBank

The Singlife Account is being discontinued: bonus returns end on 16 December 2026 and every account closes by 16 December 2027. Its formula of no-conditions returns, no lock-in and a Visa debit card is exactly what a new generation of apps now does better. We compare the six closest replacements: Chocolate Finance (2.2% p.a. on your first S$20k, with a card), Trust Bank (guaranteed 2.2% on S$100k+ fresh funds to 31 Jan 2027), GXS (Holiday Boost up to 2.4% until 30 Nov), MariBank, StashAway Simple and Syfe Cash+ Flexi, with every rate re-checked on each provider's own site on 20 November 2026.

Marcus Wong20 November 202611 min read

> Quick view: Singlife is closing the Singlife Account: bonus returns end 16 December 2026 and every account closes by 16 December 2027. The closest like-for-like replacements are no-conditions apps, led by Chocolate Finance at 2.2% p.a. on your first S$20,000 with a Visa debit card, Trust Bank's guaranteed 2.2% p.a. on S$100,000+ of fresh funds until 31 January 2027, and GXS's Holiday Boost at up to 2.4% p.a. until 30 November. We re-checked every rate on each provider's own site on 20 November 2026.

The Singlife Account is being discontinued. New applications have stopped, the 1% p.a. Booster Bonus and 0.5% p.a. Top-up Bonus end on 16 December 2026, the account's PayNow UEN stops working for merchant payments after 15 December 2026, and every remaining account closes by 16 December 2027. After the bonuses end, the account pays only its base return of 1.5% p.a. on the first S$10,000 and 1.0% p.a. on the next S$90,000, and those base rates are not guaranteed either.

So the real question is where the money should go. The Singlife Account's appeal was a specific combination: a return with no salary credit, no card spend and no monthly hoops, interest you could watch arrive, no lock-in, a Visa debit card attached to the balance, and an app that took minutes to set up. Plain bank savings accounts mostly pay their headline rates only if you credit salary and spend on cards, so this guide sticks to products that match the Singlife formula: park money, earn without conditions, withdraw any time.

How we checked: every rate, cap and deadline below was re-read on the provider's own website on 20 November 2026. Rates in this space move monthly, several of the promotions below end on 30 November or 31 December 2026, and we have flagged which part of each headline number is permanent and which is a promotion.

One safety note before the list: Trust, GXS and MariBank are MAS-licensed banks, so deposits are SDIC-insured up to S$100,000 per depositor. Chocolate Finance, StashAway and Syfe are MAS-licensed fund managers, not banks: your money buys units in low-risk money market and bond funds, is held with regulated custodians, and is not SDIC-insured. The Singlife Account itself was an insurance savings plan, which was not SDIC bank-deposit insurance either, so for most Singlife Account holders the fund-manager options are not a step down in kind, but it is worth knowing what you are buying.

Chocolate Finance: the Closest Like-for-Like, 2.2% p.a. on Your First S$20k With a Zero-FX Visa Card
1
Chocolate Finance: the Closest Like-for-Like, 2.2% p.a. on Your First S$20k With a Zero-FX Visa Card logo

Chocolate Finance: the Closest Like-for-Like, 2.2% p.a. on Your First S$20k With a Zero-FX Visa Card

THE CLOSEST LIKE-FOR-LIKE: of everything on this list, Chocolate Finance looks most like the Singlife Account you are losing: a no-conditions return on your spare cash, returns you can see credited daily, no lock-in, and a Visa debit card attached to the same balance.THE RATE: targets 2.2% p.a. on the first S$20,000 and 1.9% p.a. on the next S$130,000, so your whole first S$150,000 is covered, and up to 1.9% on anything above that, with no salary credit, no spend requirement and no subscription. A top-up programme makes up any shortfall against those targets on your first S$150,000, currently running to 30 June 2027 or until its managed account reaches S$2.5 billion, whichever comes first.THE CARD: the Chocolate Visa debit card charges zero FX fees and earns 1 HeyMax Max Mile per S$1 on your first S$2,000 of spend each month, then 0.4 Max Miles per S$1 with no cap (bill payments capped at 300 miles a month), and with an average balance of S$5,000 or more you can convert your returns into miles too.WELCOME REWARD: new customers who make a first top-up by 31 December 2026 and keep the money in for 30 days get S$5 to S$60, tiered by how much you add (S$60 needs S$80,000 or more).THE CAVEATS: Chocolate is a Capital Markets Services licensee, not a bank, so the money is in funds, not SDIC-insured deposits, and the rates are targets rather than promised interest. In March 2025 a rush of withdrawals made it suspend its instant-withdrawal feature for a stretch and pay out on its standard processing timeline instead, a useful reminder of the difference.BEST FOR: ex-Singlife users who want the nearest one-for-one replacement, card included.

Visit website
Trust Bank: the SDIC-Insured Pick, Guaranteed 2.2% p.a. on S$100k+ Fresh Funds to 31 Jan 2027
2
Trust Bank: the SDIC-Insured Pick, Guaranteed 2.2% p.a. on S$100k+ Fresh Funds to 31 Jan 2027 logo

Trust Bank: the SDIC-Insured Pick, Guaranteed 2.2% p.a. on S$100k+ Fresh Funds to 31 Jan 2027

THE SDIC-INSURED PICK: Trust is a licensed bank backed by Standard Chartered and FairPrice Group, so this is the option for money you want under SDIC insurance (up to S$100,000).THE GUARANTEE: until 31 January 2027, Trust's Level Up promotion pays a guaranteed 2.2% p.a. on S$100,000 or more of fresh funds, and 2.0% p.a. on S$25,000 to S$99,999, the only guaranteed rate at this level on this list.THE PLANS: the everyday account offers three switchable plans on a 0.05% base: Flex at up to 2.40% p.a. if you complete any three of eight bonus 'scoops' each month (things like card spend, salary credit and investing), Signature at up to 1.00%, and Zen at a flat 0.40% with no conditions at all. Interest applies on balances up to S$1.2 million, there are no monthly fees and no lock-in.THE SINGLIFE COMPARISON: Zen is the honest like-for-like (no hoops) and pays far less than Chocolate; the big rates need either six-figure fresh funds or three monthly scoops. The Trust card and app are genuinely good, and FairPrice Group perks (Link points, occasional grocery coupons) add real value if you shop there.BEST FOR: balances you want SDIC-insured, and anyone moving S$25,000+ who can catch the Level Up window.

Visit website
GXS Bank: Holiday Boost up to 2.4% p.a. Until 30 November, Then Pockets at 1.2%
3
GXS Bank: Holiday Boost up to 2.4% p.a. Until 30 November, Then Pockets at 1.2% logo

GXS Bank: Holiday Boost up to 2.4% p.a. Until 30 November, Then Pockets at 1.2%

THE RATES: GXS (backed by Grab and Singtel) pays 0.88% p.a. on the main account and 1.2% p.a. in Saving Pockets, both credited daily with no conditions, no fees and no lock-in, though the 1.2% is flagged as a limited-time promotional rate.BOOST POCKETS: lock a fixed term and you get the 0.88% base plus a maturity bonus: 1.5% p.a. total at 3 months, 1.6% at 4, 1.75% at 12 and 2.0% at 18 months, paid when the pocket matures.HOLIDAY BOOST, ENDS 30 NOVEMBER: name a new 3 or 4-month Boost Pocket 'HOLIDAY BOOST' with S$10,000 to S$100,000 of fresh funds and you get an extra 0.8% p.a. on top, so 2.3% p.a. at 3 months or 2.4% at 4 months, with the extra 0.8% paid as cashback (capped at S$575 and S$800 respectively) and a S$50 Takashimaya voucher for the first 300 pockets of S$50,000 or more.NEW USERS: S$20 cashback on a first Boost Pocket of S$5,000 or more by 31 December 2026.SINGLIFE COMPARISON: the everyday rates are lower than Chocolate's, but this is an SDIC-insured bank, the pockets map nicely onto how people used Singlife as a spare-cash pot, and the GXS debit card earns instant cashback on S$10+ spends.BEST FOR: anyone who can catch the Holiday Boost before 30 November, and pocket-style savers.

Visit website
MariBank: 3.08% p.a. on the Billboard, 0.88% in the Fine Print, and a Soft Landing for Your First 30 Days
4
MariBank: 3.08% p.a. on the Billboard, 0.88% in the Fine Print, and a Soft Landing for Your First 30 Days logo

MariBank: 3.08% p.a. on the Billboard, 0.88% in the Fine Print, and a Soft Landing for Your First 30 Days

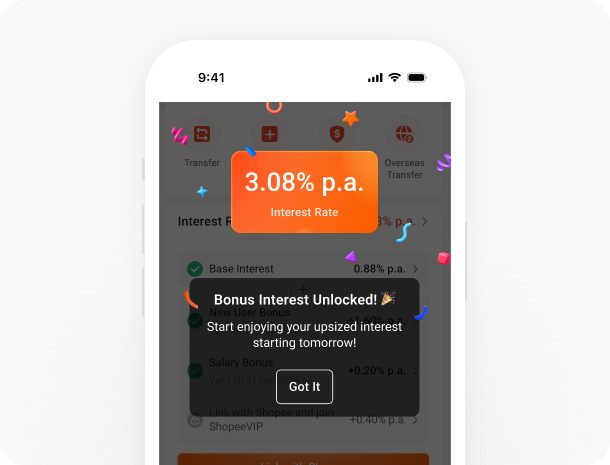
THE RATE, READ CAREFULLY: MariBank (Sea Group, the Shopee family) advertises up to 3.08% p.a., the biggest headline number in this guide, but it is a stack: a 0.88% p.a. base plus 1.60% for your first 30 days as a new user, 0.40% for subscribing to paid ShopeeVIP, and 0.20% for crediting salary. After your first month, with no ShopeeVIP and no salary switch, you are back at 0.88%.WHAT IS GOOD: interest is credited daily on the previous day's balance, there is no minimum, no fall-below fee and no lock-in, it is SDIC-insured, and the app plugs into Shopee (pay with Mari, ShopeePay top-ups, Mari Invest for spare cash into a money market fund).USD CORNER: USD balances earn a promotional 1.88% p.a. until 31 December 2026, 0.88% after.SINGLIFE COMPARISON: the 30-day 2.48% (base plus new-user bonus) is a nice landing pad for your Singlife money while you decide on a permanent home, and heavy Shopee users who would pay for ShopeeVIP anyway can hold 1.28% or more with salary. Everyone else should treat 0.88% as the real number.BEST FOR: Shopee regulars, and a soft landing in your first 30 days.

Visit website
StashAway Simple: a Projected 1.6% p.a. on Any Amount, No Caps and No Hoops
5
StashAway Simple: a Projected 1.6% p.a. on Any Amount, No Caps and No Hoops logo

StashAway Simple: a Projected 1.6% p.a. on Any Amount, No Caps and No Hoops

THE RATE: StashAway Simple holds a money market portfolio (30% LionGlobal SGD Money Market Fund, 70% LionGlobal SGD Enhanced Liquidity Fund) with a projected 1.6% p.a. net of all fees, no minimum, no cap, no lock-in and unlimited free withdrawals. The management fee (0.15% p.a.) is already inside that 1.6%.WELCOME OFFERS: new investors currently get a boosted 4.6% p.a. on their first S$10,000 in Simple for the first month, and a 3% p.a. fixed return for 6 months if they bring in S$100,000 within 30 days of signing up; StashAway's welcome terms change monthly, so read the dated terms PDF before you count on them.STEP-UPS: Simple Plus (a longer-duration bond portfolio) shows a 3.6% yield to maturity with a recommended 12-month-plus holding period, and Simple Guaranteed fixes a rate for a 1 to 12-month term.SINGLIFE COMPARISON: no card and no insurance cover, but it is the cleanest home for a balance too big for the bonus caps elsewhere: the 1.6% applies to the whole balance, whether that is S$5,000 or S$500,000. Not SDIC-insured; funds sit with custodians in your name.BEST FOR: six-figure balances and set-and-forget parking.

Visit website
Syfe Cash+ Flexi: a Projected 1.7% p.a., the Highest Robo Rate, With a Guaranteed 1.6% Option
6
Syfe Cash+ Flexi: a Projected 1.7% p.a., the Highest Robo Rate, With a Guaranteed 1.6% Option logo

Syfe Cash+ Flexi: a Projected 1.7% p.a., the Highest Robo Rate, With a Guaranteed 1.6% Option

THE RATE: Syfe Cash+ Flexi (SGD) projects 1.7% p.a. after all fees, the higher of the two robo cash accounts here, invested in low-risk money market funds with returns accrued daily, no lock-in, no minimum balance and unlimited free withdrawals. The management fee (0.05% to 0.15% p.a.) and a 100% trailer-fee rebate are already reflected in the 1.7%.THE GUARANTEED OPTION: Cash+ Guaranteed pays a fixed 1.6% p.a. for a 3 or 6-month term with no minimum, Syfe's answer to a fixed deposit, with the rate locked at placement.USD CORNER: Cash+ Flexi (USD) projects 3.8% p.a. if you are happy to hold US dollars (US$10,000 minimum).SINGLIFE COMPARISON: like StashAway, there is no card and no insurance, and it is a Capital Markets Services licensee rather than a bank, so no SDIC. What you get is a slightly higher projected rate than Simple's 1.6%, the option to flip part of the money into the guaranteed 1.6% tranche, and an SRS-eligible version. Projected means projected: the rate moves with Singapore money market yields, in both directions.BEST FOR: parking at the highest no-conditions robo rate, with a guaranteed tranche one tap away.

Visit website

Singlife Account alternatives compared, every figure re-checked on the provider's own site on 20 November 2026

ProviderHeadline rate (p.a.)The permanent partSDIC insured?Debit card?Minimum
Chocolate Finance2.2% first S$20k, 1.9% next S$130kTarget rate, top-up programme to 30 Jun 2027No (fund, regulated custodians)Yes, zero FX + Max MilesNone
Trust BankGuaranteed 2.2% on S$100k+ fresh funds to 31 Jan 2027; Flex up to 2.40%Zen 0.40% no-hoops; Flex needs 3 monthly scoopsYes, up to S$100kYesS$25k for the 2.0% promo tier
GXSHoliday Boost 2.3% to 2.4% to 30 Nov (3 or 4-month pocket)0.88% main, 1.2% pockets, 2.0% 18-month Boost PocketYes, up to S$100kYes, instant cashbackS$10k fresh funds for the boost
MariBankUp to 3.08% stacked0.88% base (bonuses: 30 days new user, ShopeeVIP, salary)Yes, up to S$100kNo (pays via app)None
StashAway Simple1.6% projected net; welcome boosts for new investors1.6% projected, whole balance, no capNo (money market funds)NoNone
Syfe Cash+ Flexi1.7% projected net; Guaranteed option 1.6% fixed1.7% projected, whole balance, no capNo (money market funds)NoNone

Which one should you pick?

  • You want the closest thing to the Singlife Account, card and all: Chocolate Finance. Same no-hoops formula, higher rate than Singlife's dying base return, and the only alternative here with a comparable Visa debit card. Accept that it is a fund, not a bank.
  • You want SDIC insurance and have S$25,000 or more to move: Trust's Level Up guarantee (2.0% to 2.2% p.a. to 31 January 2027) is the strongest insured rate, and Zen keeps a no-hoops trickle after that.
  • You can move this week: GXS's Holiday Boost (2.3% to 2.4% p.a., fresh funds, paid partly as capped cashback) ends 30 November 2026.
  • Your balance is six figures: StashAway Simple or Syfe Cash+ Flexi apply their whole rate to the whole balance, no caps.
  • You live on Shopee: MariBank, with eyes open about the 0.88% long-run base.
  • You only want the insurance part of Singlife: none of these replace the death and terminal illness cover. A standalone term life plan is the proper substitute, and it will cover far more than the Singlife Account's small built-in sum.

Whatever you choose, do the one Singlife housekeeping step first: link a valid bank account in the Singlife app, because that is where your remaining balance gets paid when the account closes. Full closure timeline in our Singlife Account closure guide.

The fine print

  • All rates, caps and deadlines re-checked on each provider's own website on 20 November 2026. These numbers move monthly; treat anything you read elsewhere (including older articles) as stale until you see it on the provider's page.
  • Projected and target rates (Chocolate Finance, StashAway, Syfe) are not guaranteed and can change without notice. Bank promotional rates (Trust Level Up, GXS Holiday Boost, MariBank bonuses) have their own T&Cs, fresh-funds definitions and caps.
  • This article is general information, not financial advice. Check the latest terms with each provider before moving money.

Cover photo: Pexels.

Related reads
Frequently Asked Questions

Do I need to move my Singlife Account money now?

You have until 16 December 2027 before accounts close, but the practical deadline is 16 December 2026, when the 1% Booster Bonus and 0.5% Top-up Bonus end. From that day the account pays only an unguaranteed 1.5% p.a. on the first S$10,000 and 1.0% on the next S$90,000, which the alternatives in this guide beat. There is no penalty for withdrawing early, so most people should move once the bonuses stop, and everyone should link a valid bank account in the Singlife app now so the final balance has somewhere to go.

Which alternative is most similar to the Singlife Account?

Chocolate Finance. It is the same formula: a no-conditions return on spare cash (currently a 2.2% p.a. target on the first S$20,000 and 1.9% on the next S$130,000), returns credited daily, no lock-in, and a Visa debit card attached to the balance, with zero FX fees and HeyMax Max Miles on spend. The important difference is that Chocolate is an MAS-licensed fund manager rather than a bank or insurer, so the money sits in money market and bond funds and is not SDIC-insured. If SDIC insurance matters more to you than the card, Trust Bank is the closer fit.

Is Chocolate Finance safe?

It is MAS-licensed (Capital Markets Services licence) and your money buys units in short-duration fixed income funds held with regulated custodians such as HSBC and State Street, segregated from Chocolate's own assets. It is not a bank: no SDIC insurance, capital not guaranteed, and the 2.2% is a target the top-up programme supports rather than promised interest. In March 2025 a surge of withdrawals made it suspend instant withdrawals for a period and process them on the standard timeline instead; customers were paid, but it shows the liquidity difference between a fund and a bank. Reasonable practice: keep your SDIC-insured buffer at a bank and use Chocolate for the spare-cash layer, which is how most people used the Singlife Account anyway.

Can anything still pay what the Singlife Account paid in its heyday?

Not without conditions. With both bonuses, the Singlife Account paid up to 3.0% p.a. on the first S$10,000 until 16 December 2026, and in its 2020 launch era it famously paid 2.5% when banks paid nearly nothing. In late 2026's lower-rate environment, the best no-conditions rates are Chocolate Finance's 2.2% target and Syfe's 1.7% projected. Higher numbers exist but each has a catch: MariBank's 3.08% needs stacked bonuses including a paid ShopeeVIP subscription, Trust's 2.40% Flex needs three monthly tasks, GXS's 2.4% Holiday Boost ends 30 November and pays part of the rate as capped cashback, and StashAway's 4.6% welcome boost lasts one month on S$10,000. If you can lock money away instead, compare the best fixed deposits, which pay around 2.1% for 12 months.

#singlife account alternative#singlife account closing what to do#singlife account replacement#chocolate finance vs singlife#where to put money after singlife account#best no conditions savings singapore#chocolate finance review 2026#trust bank level up promo#gxs holiday boost 2026#maribank vs chocolate finance#stashaway simple vs syfe cash plus#singlife account closure 2027#best place to park spare cash singapore

You Might Also Like